★★★★★
ckvonk
Verified Zillow review
Hedda and her team were incredible from start to finish — I felt completely supported and advocated for while making an offer and negotiating with the sellers.
The best realtor for a first-time buyer in Downtown San Diego is a local agent who understands condos closely. Someone who reads an HOA budget with you, confirms a building is warrantable, and calculates your real monthly cost before you get attached to a unit. At Palisade Realty, that is the work we enjoy doing beside you.
Palisade Realty is our name, an independent San Diego brokerage (CA DRE #01848565) with Hedda Parashos at the helm as owner and president. Downtown San Diego (92101) ranks among the markets we know best, and we would rather walk it with you. For a first purchase, downtown behaves like many small markets stacked together. Most first-time buyers tell us they wanted a realtor who names the trade-offs from one tower to the next.
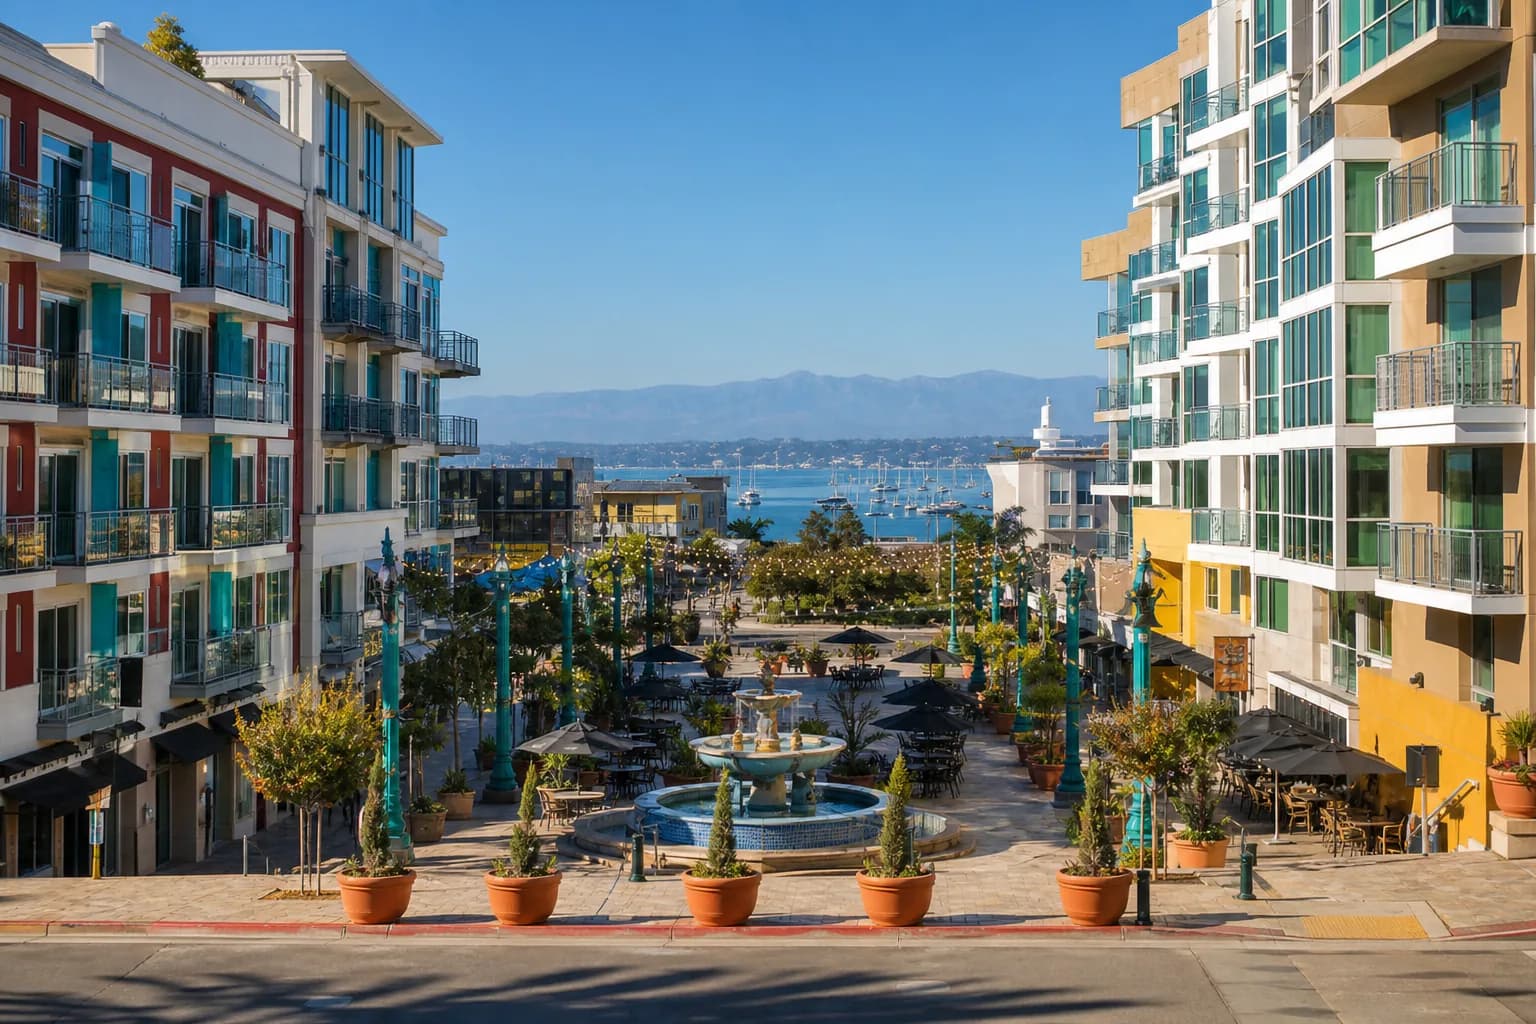
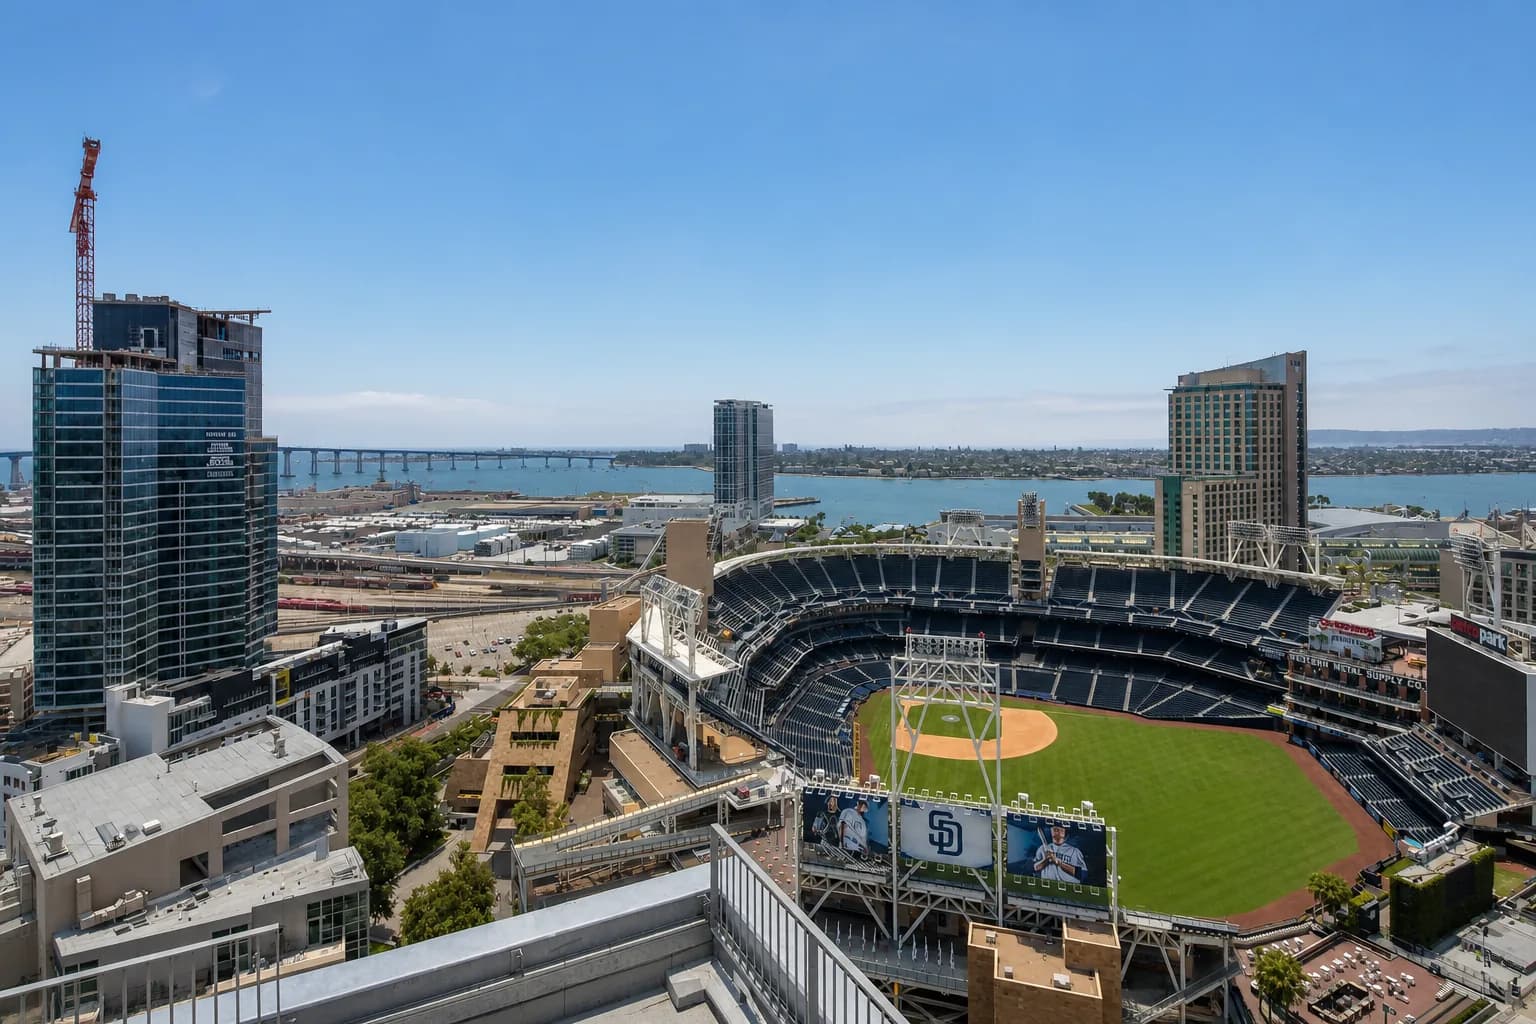
Those trade-offs start with geography. It seems like one downtown, but it is not a single market. It splits into distinct condo neighborhoods, and the right fit shifts block by block. Here is how we, your Downtown San Diego realtor, think about the main ones:
| Neighborhood | Typical home type | Best first-time buyer fit |
|---|---|---|
| Marina & Columbia | High-rise condos | Buyers wanting walkable, near-office living |
| Cortez Hill | Walk-up condos | Buyers seeking a quieter downtown price point |
| Little Italy | Boutique condos | Buyers who prize dining and market weekends |
| East Village | Lofts | Buyers who want extra space and light |
Once you settle on a neighborhood, the building becomes the next question. A tower financed a few years ago can carry very different HOA reserves than one built a decade earlier. That gap changes what your lender will fund. When you are ready, we pull the current reserve study before you write an offer.
Reading a reserve study is one piece of condo homework that quietly derails deals. We handle the rest too. Here is what we take off your plate:
Because we are an independent brokerage with more than 100 agent partners, we can pair you with a realtor who lives and works in the neighborhoods you are considering. When we suggest a full reserve study, we mean we will read it with you.
That reading follows a routine. Before you offer on any downtown building, we review five numbers that decide whether your loan will fund and whether assessments are likely:
| Item to review | Why it matters | Red flag |
|---|---|---|
| Reserve funding % | Predicts special assessments | Under 10% funded |
| Owner vs. renter mix | Affects loan eligibility | Under 50% owner-occupied |
| Litigation status | Can block financing | Active structural suit |
| Delinquency rate | Signals HOA health | 15%+ owners behind |
| Insurance coverage | Protects your equity | Gaps after recent claims |
A building can look beautiful and still fail a warrantability test. Flagging these numbers early spares most first-time buyers from chasing a home their lender would later reject.
Not every buyer needs this level of scrutiny. First-time buyers downtown tend to feel the paperwork most. You are the kind of buyer we had in mind if you are:
When it is a first purchase, we are glad to tour with a pre-approval already in hand. That lets you negotiate from strength, not guesswork.
Negotiating from strength gets easier when your financing includes help you did not know existed. Downtown San Diego offers real down payment and closing-cost assistance that some first-time buyers overlook, and it can lower your costs when your income qualifies. These are the programs we check for you:
| Program type | What it can do | Who it fits |
|---|---|---|
| SDHC down payment assistance | Deferred help toward down payment | Income-qualified county buyers |
| First-time buyer loan programs | Lower rate or reduced down payment | Buyers under income limits |
| VA loan | Zero down, no PMI | Eligible service members |
| FHA loan | 3.5% down | Buyers building credit |
Before you assume you do not qualify, let us check your income against the current limits. A single program can raise your affordable price by tens of thousands. Even a small rate difference changes your monthly payment.
Assistance can widen your options, yet downtown ownership still asks you to weigh some real trade-offs. Buying a first condo with us gives you a clear cost picture and a building vetted before you offer, though condo life carries costs worth naming. Here is the honest balance.
What works in your favor:
What to weigh honestly:
Some first-time buyers worry about overpaying early or being handed off to whoever is free. We understand that concern. We start with pre-approval, review the building, and stay with you as one accountable realtor from the first showing to the keys.
What credit score do first-time buyers need to buy a condo downtown?
Many first-time buyers qualify with a score around 620 for FHA and higher for conventional loans. Your income, debts, and the building's approval status all factor in, which is why we connect you with a local lender to confirm before you tour.
Are HOA fees worth it in Downtown San Diego?
For most downtown condos, yes, because dues cover building insurance, amenities, and maintenance you would otherwise pay separately. The key is confirming the reserves are funded. We read every budget with you so your dues are buying real financial health.
Can I use a VA loan on a downtown condo?
Yes, as long as the building carries VA condo approval. Not every tower does. We verify eligibility first and keep eligible service members from losing time on a home that cannot close.
How much home can a first-time buyer afford downtown?
It depends on your income, debts, and down payment, along with HOA dues and parking. We run those real numbers with you before you shop, and assistance programs can raise that budget more than many first-time buyers expect.
Showing 2 of 993 reviews. Rating and total above cover all reviews.
Hedda and her team were incredible from start to finish — I felt completely supported and advocated for while making an offer and negotiating with the sellers.
Hedda is the best realtor I have ever had — a true client's advocate who goes above and beyond, enthusiastic but never pushy.
When you are ready to begin, tell us the Downtown San Diego neighborhoods and price range you have in mind, and we will set up a relaxed first conversation. Get pre-approved, see what your budget really buys, and start touring with a realtor beside you. Call Palisade Realty to start your first-time buyer search, and let us find your first San Diego home together.